
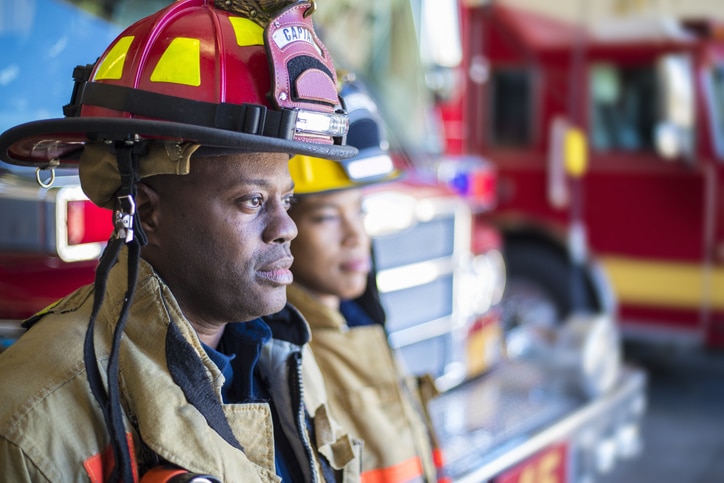
Working as a firefighter, paramedic, law enforcement officer, or emergency medical technician puts the body and mind through stress that most occupations never come close to replicating. Long shifts, physical exertion, exposure to hazardous materials, and the psychological weight of the job create a health profile that standard employer group plans are not always designed to handle well. Understanding what coverage options exist, how they differ, and what first responders should specifically look for can make a real difference when it comes time to use that coverage.
Why First Responders Have Unique Health Needs
The occupational risks faced by first responders go well beyond what most workers encounter. Firefighters, for example, face elevated rates of certain cancers linked to smoke and chemical exposure. According to the International Association of Fire Fighters, cancer is now the leading cause of death among firefighters in the line of duty in the United States. Law enforcement officers carry a disproportionate burden of cardiovascular disease, partly attributed to shift work, stress hormones, and disrupted sleep patterns. EMTs and paramedics face high rates of musculoskeletal injury from patient handling, as well as significant rates of post-traumatic stress and burnout.
These realities mean that a health plan built around primary care visits and routine prescriptions may leave major gaps. First responders often need access to occupational medicine specialists, behavioral health resources, orthopedic care, and cancer screening programs. When evaluating any plan, those specific categories deserve close attention.
Types of Health Coverage Available to First Responders in California
California first responders typically have access to several distinct channels for health coverage. Each comes with its own trade-offs in terms of cost, flexibility, and the depth of benefits offered.
Employer-Sponsored Group Plans
Many first responders receive coverage through their employing agency, whether a city, county, or special district. These group plans are often negotiated through collective bargaining agreements and can be quite comprehensive. CalPERS, California’s Public Employees’ Retirement System, administers health benefits for many state and local government workers, including a large number of public safety employees. CalPERS offers several plan tiers with varying premiums and network sizes. The advantage here is that employer contributions often reduce the out-of-pocket premium burden significantly. The limitation is that the worker typically has to choose from a fixed menu of plans and may not be able to customize coverage beyond what the agency offers.
Union-Negotiated Benefits
For unionized first responders, the collective bargaining agreement often determines both which plans are available and how much the employer must contribute toward premiums. Strong union contracts can secure access to plans with low deductibles, robust prescription coverage, and mental health benefits that match medical benefits dollar for dollar, as required under mental health parity laws. First responders who are union members should review their contract carefully before assuming employer-sponsored is the only or best option.
Specialized and Supplemental Plans
Some organizations specifically design health plans with first responders in mind, accounting for the occupational hazards and behavioral health pressures unique to the profession. These plans may include features like critical illness riders, enhanced behavioral health coverage, or telehealth access designed around shift schedules that make traditional office hours impractical. Supplemental plans can also fill gaps left by primary coverage, such as income protection during a work-related injury or specialized cancer coverage relevant to firefighters.
Key Coverage Categories to Evaluate
When comparing health plans, first responders should look at more than just the premium. The following categories tend to matter most given the nature of the job.
| Coverage Category | Why It Matters for First Responders | What to Look For |
| Behavioral Health | High rates of PTSD, depression, and burnout in the profession | Parity with medical benefits; confidential access; telehealth options |
| Occupational Medicine | Work-related injuries and exposures are common | In-network occupational health specialists; workers’ comp coordination |
| Cancer Screening | Elevated cancer risk, especially for firefighters | Early and frequent screenings; coverage for occupational cancer diagnoses |
| Cardiovascular Care | Elevated heart disease risk from stress and shift work | Preventive cardiology; stress testing; low cost-sharing for diagnostics |
| Orthopedic and Physical Therapy | Physical demands lead to musculoskeletal injuries | Generous PT visit limits; access to sports medicine specialists |
| Prescription Drug Coverage | Chronic condition management and post-injury medications | Low copays on generics; formulary that covers common first responder medications |
Understanding Costs Beyond the Premium
The monthly premium is just one part of the cost equation. First responders evaluating plans should pay close attention to deductibles, out-of-pocket maximums, copays, and coinsurance rates. A plan with a low premium but a $5,000 individual deductible can become extremely expensive for someone who gets injured on the job and needs surgery, physical therapy, and follow-up care in a single calendar year.
Out-of-pocket maximums cap the total annual spending and represent the most important safety net for high-cost care scenarios. In 2024, the ACA-set out-of-pocket maximum for individual coverage on marketplace plans was $9,450, according to the Centers for Medicare and Medicaid Services. Employer and specialized plans may set lower limits. For first responders with physically demanding jobs, choosing a plan with a lower out-of-pocket maximum often makes financial sense, even if the premium is somewhat higher.
Networks also deserve scrutiny. A plan that only covers in-network care can create problems if the nearest specialist for a specific condition is out of network. First responders who live in rural or semi-rural parts of California, far from major medical centers, should check network coverage in their specific area before enrolling.
Mental Health Coverage: A Priority, Not an Afterthought
First responder mental health has received growing attention in recent years, and for good reason. A 2018 study published in the Journal of Emergency Medical Services found that EMTs and paramedics experience PTSD at rates between 14 and 22 percent, compared to roughly 3.5 percent in the general population, according to the U.S. Department of Veterans Affairs. Firefighters and law enforcement officers face similarly elevated risks.
California law and federal mental health parity regulations require that health plans cover mental health and substance use disorder benefits at the same level as medical and surgical benefits. In practice, the quality of mental health networks and the confidentiality of services can vary widely between plans. First responders, particularly those in smaller agencies where everyone knows each other, often have concerns about confidentiality when seeking mental health care through work-linked plans. Some specialized plans and employee assistance programs offer more discreet access, which can meaningfully increase the likelihood that a person actually uses the benefit when they need it.
How to Research and Compare Your Options
The process of comparing health plans does not have to be overwhelming if broken into clear steps. Start with what the employer or union actually offers, then assess whether those options meet the specific needs outlined above. If gaps exist, look into supplemental plans that can layer on top of primary coverage.
- Request a Summary of Benefits and Coverage (SBC) document for each plan option. This standardized document makes side-by-side comparisons much easier.
- List your most-used healthcare services from the past two to three years and check how each plan covers those specific services.
- Verify that your preferred providers or specialists are in-network under each plan.
- Calculate the worst-case annual cost by adding the annual premium to the out-of-pocket maximum for each plan.
- Check behavioral health network depth separately, since mental health provider networks are often narrower than medical networks.
- Ask your union representative or HR department whether any first-responder-specific plans or riders are available that you may not have considered.
Organizations that focus specifically on first responder health can also be a valuable resource during this process. For California-based first responders looking for plans designed around the realities of the profession, it is worth taking time to learn more about First Responders of California, which structures its offerings around the distinct occupational health needs of those who serve in public safety roles.
Planning for the Long Term: Retirement and Continued Coverage
Many first responders retire earlier than the general workforce, sometimes in their 50s, which creates a coverage gap between retirement and Medicare eligibility at age 65. CalPERS offers retiree health benefits for qualifying public employees, but the specific terms depend on years of service, the employer’s contract with CalPERS, and when the employee retires. First responders who plan to retire before 65 should understand exactly what their retiree health benefits look like before making retirement decisions, since the cost of purchasing individual or marketplace coverage for a decade or more can be substantial.
Some agencies also provide supplemental retiree benefits through union trusts or retiree health accounts. These can offset the cost of premiums during the pre-Medicare years. Building a clear picture of post-retirement health costs is just as important as understanding active-duty coverage.
Putting It All Together
Health coverage for first responders is not a one-size-fits-all matter. The physical demands, occupational hazards, mental health pressures, and career timelines that define this work create a distinct set of needs that general consumer health plans were not necessarily built to address. By understanding the types of coverage available, examining the right categories with care, and factoring in both immediate and long-term costs, first responders in California can make informed decisions that genuinely protect their health and financial stability. The effort spent evaluating options carefully upfront tends to pay off considerably when care is actually needed.

